Because the Other Driver’s Insurance Isn’t Always Enough

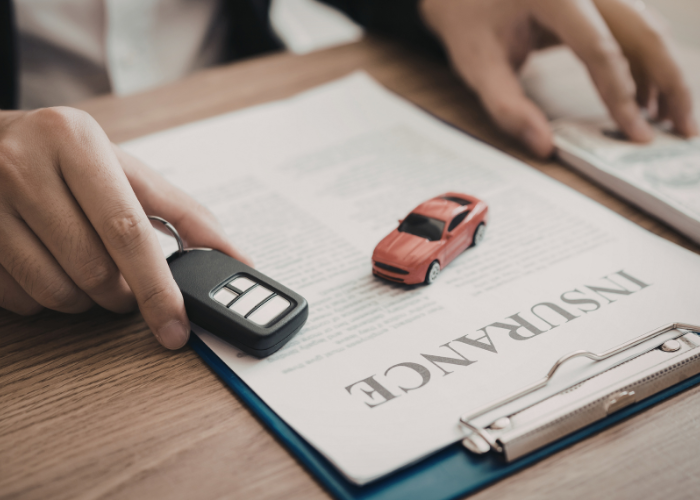
One accident without collision coverage can cost more than years of premiums.
You pull out of a parking spot and clip a concrete post. A distracted driver runs a red light and T-bones your passenger side. You swerve to avoid debris on US-41 and slide into a guardrail.
In every one of those scenarios, someone has to pay for the damage to your vehicle. Without collision coverage, that someone is you.
One accident without collision coverage can cost more than years of premiums. You pull out of a parking spot and clip a concrete post. A distracted driver runs a red light and T-bones your passenger side. You swerve to avoid debris on US-41 and slide into a guardrail. In every one of those scenarios, someone has to pay for the damage to your vehicle. Without collision coverage, that someone is you.
Collision insurance pays to repair or replace your vehicle when it’s damaged in a crash — whether you hit another car, another car hits you, or you collide with a stationary object. It applies regardless of who caused the accident.
Like comprehensive coverage, collision is not required by Florida state law. The state minimum only mandates PIP and PDL. But if you’re financing or leasing your vehicle, your lender will require collision coverage. And for most drivers, the cost of going without it far exceeds the cost of carrying it.
Accidents with Other Vehicles
Whether you’re at fault or the other driver is, collision coverage pays for your vehicle’s repairs. This matters most when the other driver is uninsured — and in Florida, roughly one in five drivers carries no coverage at all.
Collisions with Stationary Objects
Guardrails. Light poles. Mailboxes. Parking bollards. Concrete barriers. If your vehicle hits a fixed object, collision coverage pays for the damage.
Rollover Accidents
If your vehicle rolls over — whether from a sharp turn, overcorrection, or a blown tire — collision coverage applies.
Pothole and Road Damage
Hitting a pothole deep enough to bend a rim or crack an axle? Collision coverage handles it. In Florida, road construction zones and post-storm road damage make this more common than you’d think.
Single-Vehicle Accidents
You don’t need another car to be involved. If you slide off the road in a rainstorm or swerve to avoid something and hit a tree, collision covers your vehicle’s damage.
Collision has a defined scope. It does not pay for:
Non-collision damage — theft, vandalism, weather, falling objects, and animal strikes are covered by comprehensive insurance, not collision
Damage to other people’s vehicles — your Property Damage Liability covers that
Your medical bills — PIP, MedPay, or health insurance covers your injuries
Mechanical failure — engine problems, transmission failure, or normal wear aren’t covered by any auto insurance
Collision coverage includes a deductible — the amount you pay before your insurance covers the rest of the repair bill.
Common deductible options: $250, $500, $1,000
Here’s the math in plain terms:
| Deductible | Your Cost at Claim Time | Monthly Premium Impact |
|—|—|—|
| $250 | Low out-of-pocket | Higher monthly payment |
| $500 | Moderate out-of-pocket | Moderate monthly payment |
| $1,000 | Higher out-of-pocket | Lower monthly payment |
If you have savings set aside for emergencies, a higher deductible can lower your premium significantly. If cash flow is tighter, a lower deductible gives you more predictability. We help you find the balance.
These two coverages work side by side but cover different events:
| Scenario | Covered By |
|—|—|
| You hit another car | Collision |
| A tree falls on your car | Comprehensive |
| You hit a guardrail | Collision |
| Your car is stolen | Comprehensive |
| You roll over in a ditch | Collision |
| Hail dents your roof | Comprehensive |
| A pothole bends your rim | Collision |
| Your windshield cracks from debris | Comprehensive |
Most drivers who carry one also carry the other. Together, they form what’s commonly called “full coverage.”
You should strongly consider collision coverage if:
Your vehicle is financed or leased (your lender will require it)
Your car is worth more than a few thousand dollars
You couldn’t afford to replace your vehicle out of pocket after a total loss
You drive in high-traffic areas (Fort Myers, Cape Coral, Naples)
You commute daily and log significant miles
Collision coverage may not be necessary if:
Your vehicle’s market value is very low and the annual premium approaches or exceeds that value
You have substantial savings to self-insure a total loss
Our agents run the numbers with you so the decision is based on facts, not guesswork.
We’re not the insurance company. We’re your agent — and that distinction matters.
Independent, not captive. A captive agent sells one company’s products. We represent dozens of carriers, which means we can shop the entire market and find the policy that actually fits your situation.
Local, not remote. Our office is at 702 Leeland Heights Blvd W in Lehigh Acres. We serve Lee and Collier Counties — Lehigh Acres, Fort Myers, Cape Coral, Bonita Springs, Estero, and Naples. You’re not a policy number. You’re a neighbor.
Family-owned since 2009. Butch Swank built this agency on one idea: change the way people feel about their insurance agency. Our team — Butch, Stephanie, Mary, and the rest — treats every client like family, because that’s how this business should work.
Community-rooted. Butch serves on the Board of Lehigh Regional Medical Center, co-founded the East Lee Education Cooperative, and established the Watch D.O.G.S. program at Lehigh Elementary. Mary sits on the Board for Lehigh Community Services. We don’t just work here — we live here.
We insure primary homes, secondary and seasonal homes, condo units, as well as property you own and rent to others.
We provide coverage for cars, motorcycles, motor homes and recreational vehicles. We provide the best price and coverage.
Our business is protecting your business from the risks you face everyday, whether your business is large or small.
At Goodlad & Swank, we are proud to offer a full suite of insurance options.
Find out your risk and get protected. We offer coverage through the National Flood Insurance Program as well as private insurance carriers.
Whether life insurance is needed for your family or your business we can help you find the right policy at the best possible price.
Your property’s risk of damage from a hurricane in Florida is elevated. If the past has taught us anything, it’s to be prepared.
If you are a renter, you should have renters insurance. You will get the coverage you need at a price that fits your budget.

We not only help clients prepare for the unknown. We also provide various resources to understanding Florida’s Insurance options. Through our partnerships with top rated insurance companies, our affiliations and community resources, we can help you navigate through the insurance world.
Don’t just take our word for it. We’re proud to be able to serve our customers.

This is an amazing company to do business with. I have several properties and slowly I have changed all properties to be with Goodlad & Swank Insurance.
Fast, courteous, professional service with comparable rates. What else do you need?