Take care of your Lehigh Acres home by learning about all your options for homeowner’s insurance coverage

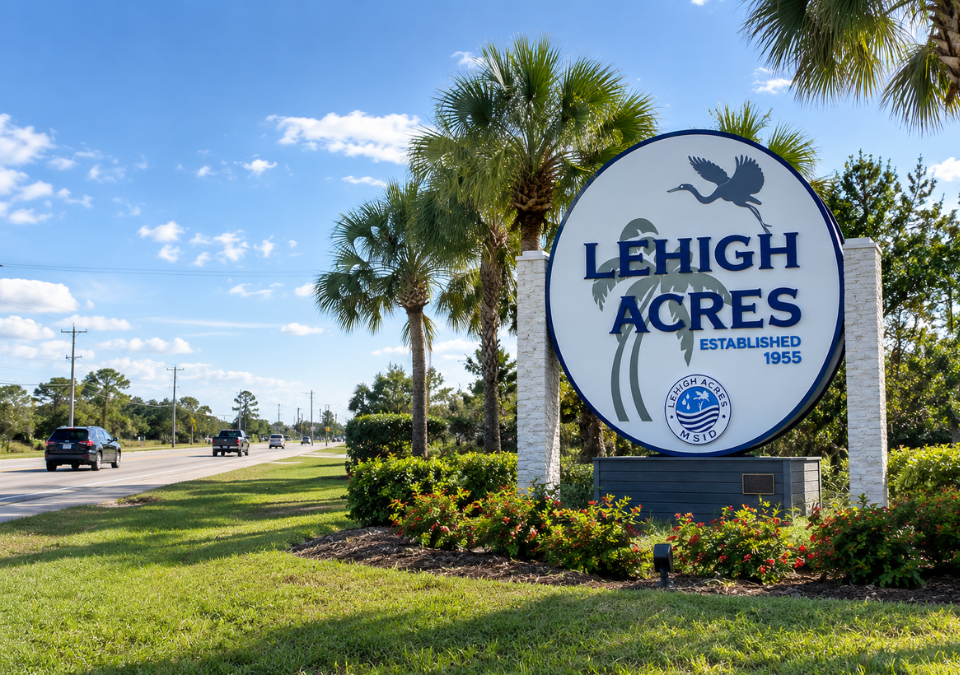
Lehigh Acres is rapidly growing and is one of Southwest Florida’s most buildable cities. As a homeowner, your home is precious to you, and that is why we encourage you to learn and consider options for your homeowner’s insurance.
Dwelling Coverage | Covers damage from fire, storms, or other circumstances.
Other Structures | Covers other structures on the property such as a detached garage, playground set, patio or deck, or storage building like a shed.
Personal Property | Covers losses of your personal items and contents of your home.
Additional Living Expenses | Provides cash for relocation if your home is destroyed or if it is unlivable during repairs.
Personal Liability | Coverage in the event that someone gets injured on your property, or if your property is damaged through your fault.
Medical Payments | Covers the cost of medical bills, ambulances, surgical expenses, and more if someone visits your home and gets hurt.
While homes are more affordable in Lehigh Acres, Florida homeowners know how expensive insurance can be. But why is homeowner’s insurance so expensive in Florida? This is due to a few things. Our tropical weather, while amazing, leaves us more prone to being hit by hurricanes, while other states do not carry as much of a risk.
There are also a few reasons why premiums are rising nationwide. The continuous supply chain disruptions for building materials such as lumber have driven the cost of repairs and rebuilds up nationally, and Florida is no exception. There is also an increasing number of insurance fraud cases each year, so the losses and legal costs are being passed on to customers.
Florida’s average cost of homeowner’s insurance in Florida is around $1,405 annually or $118 monthly as of 2022. Compared to the rest of the country, Florida homeowners pay around 5% more in premiums per year. Of course, these numbers will vary depending on a number of factors.
A major part of calculating the monthly or annual cost of homeowner’s insurance depends on your deductible. The higher your deductible, the lower your premium and vice versa. The most common deductible tier is $500 or $1,000 but oftentimes you can save on your premium by making a small leap in your deductible.
The replacement cost of your house, the age of your house, the age of your roof, and the location of your house are all also major components that are used to calculate pricing.
We work with almost every home insurer in Florida, so we are able to shop around and compare coverages depending on your needs, allowing us to offer you some of the best homeowners insurance rates in Lehigh.
Your Home (Dwelling Coverage)
A hurricane eats your roof. A BBQ accident goes awry and burns your back porch and living room. Someone throws a chair through a slider, steals some belongings and trashes your house while you’re relaxing in Islamorada on vacation. In any of these situations, you’ll be happy to took the time to get home insurance. Most basic homeowner’s insurance policies include dwelling coverage which covers the cost to repair or rebuild due to damage such as:
Other Structures Coverage
This coverage is for things like a shed, gazebo, swimming pool, detached garage or backyard fence on your property. With other structures coverage, your policy will cover a percentage of the Dwelling Coverage — it’s typically around 10% so if you have items listed above and they are higher value it is important to share that with your agent. A $350,000 house would have $35,000 of Other Structures coverage in a normal policy.
Keep in mind it would be nice to have this coverage on your property for the things that might not be part of your primary dwelling, but would still incur an expense to replace if they sustained damage. Bear in mind additional coverage is also available for more complex structures like a pool house or guest house. Let your agent know so we can accurately calculate the coverage amounts.
Personal Property
If it’s the dry season and a wildfire in the neighborhood burns your house to the ground, you’ll need help replacing things beyond just your house. What about that new sofa you love so much? Or that amazing 80” Sony TV needs to watch The Mandalorian? That is barely scratching the surface. You would need new clothes, new cups, new China, a new cooler, new chairs…. I’m running out of C words, but you get the point.
This coverage protects your possessions inside your house that help make it a house. On thing else to keep in mind is that expensive items like art and jewelry are covered but there is usually a dollar limit on them. If you have these it might be worth looking into a Personal Items Policy which is designed to cover such items.
Liability Coverage
Liability insurance covers you against any lawsuits for bodily injury or property damage in your home. This coverage will pay for legal representation and could also cover damages you’ve been deemed responsible for in court.
Personal liability insurance provides coverage for you, your home, and your guests in the event of an accident or bodily injury. Legally, you are the responsible party for damages and medical payments if a guest in your home is injured, regardless of the accidental nature of the event. You might also be liable for accidents that occur away from your property if your family is the cause, or if family members who live with you are responsible. Personal liability protection covers legal defense costs and damages if you are sued and also applicable medical payments.
Additional Living Expenses
We had clients suffer major damage to their houses from Hurricane Irma. The Additional Living Expense covers the cost of hotel bills and restaurants bills while you’re forced to stay away from home until things are fixed.
It is meant to help you pay for costs over and above your usual living expenses you take on while your home gets rebuilt or repaired. One client had a big pine tree basically cut his house in half. He was quite happy this coverage allowed him to maintain a decent quality of life while the contractor got busy.
Flood
When the water start rising, hopefully you are in a safe place and have flood insurance in place. This is because standard home insurance policies do not cover flood damage to your home. If you live in a designated flood zone, you should have a flood insurance policy and also a home insurance policy. If you live in a preferred flood risk area there is still a chance of flooding – 30% of claims come from non-flood zones. The preferred risk policies are very reasonable – typically around $450 annually for $250,000 in coverage.
Earthquakes
I get it. We live in Florida and who worries about earthquakes? The answer is not many people and there are very few annually and most occur in the Panhandle. Regardless, they do happen and would require a separate policy to cover damages.
Sinkholes
Most polices will offer Catastrophic Ground Collapse coverage. This is the coverage that should step up if your house disappears overnight in a hole in the ground. The separate Sinkhole coverage is more for the slow and subtle shifting of the ground beneath your house’s foundation. This often can cause only cosmetic damage that is very costly to repair, so it’s typically not offered. In fact, there are some carriers that might limit all of these coverages if your house is located near a known and active sinkhole area.
Maintenance
Termites, old and peeling roof shingles, leaky water pipes and prior damage are all things home insurance usually won’t cover. Taking steps to maintain your home and showing pride of ownership are important for a number or reasons. Your home is a big investment and should be treated with love and care. The home insurance policy is not designed to cover things that should be the owners responsibility.
Looking for reliable protection for your most cherished investment? Look no further than Goodlad and Swank Home Insurance. Our policies are crafted with your peace of mind in mind. Picture this: a comprehensive shield against unforeseen disasters, safeguarding not just your home but your sense of security too. With Goodlad and Swank, you’re not just purchasing insurance; you’re investing in trust, reliability, and a promise to protect what matters most to you.
What sets Goodlad and Swank apart in the realm of home insurance is our unwavering commitment to personalized service. We understand that every home is unique, carrying its own set of risks and vulnerabilities. That’s why our team works tirelessly to tailor solutions that fit your specific needs like a glove. Whether it’s coverage for natural calamities, theft, or structural damages, we’ve got you covered. Our goal is not just to sell insurance but to build lasting relationships with our clients, ensuring that you feel supported and secure every step of the way.
Beyond the security of knowing you’re covered, choosing Goodlad and Swank Home Insurance means gaining access to a network of support and resources designed to make your homeowner journey as seamless as possible. From streamlined claims processing to expert advice on risk mitigation, we’re here to empower you to make informed decisions about your property. Don’t leave the protection of your home to chance. Join the countless homeowners who have entrusted Goodlad and Swank for their insurance needs and experience the difference today.
Homeowners’ insurance laws and regulations are constantly changing. It is important to know what is and what isn’t covered in your policies. Here are some additional options to consider:
Jewelry, Guns, Fine Art Collections. Let’s face it, every home contains items that would interest a burglar. Family heirlooms or just that giant 80” TV on the wall can be covered. Be sure to let our representatives know if you have high-dollar items. There are limits to the amount offered on this coverage so it’s important to detail what you have. Sometimes we can build a list outlining all of the items and in certain cases, we can write you a special policy called a Personal Articles Policy to provide the proper coverage amounts.
Flood Coverage. Roughly 30% of flood claims occur in places that are “not in a flood zone”. This coverage does NOT come standard with your homeowners’ insurance, so it is important to have in Florida. Essentially, all of Florida is a flood zone with certain areas more prone to flooding than others. Also, keep in mind that if you are in certain flood zones banks require this coverage. It’s important to check with an agent to determine pricing before buying a home. The cost of the policy could be so high that it affects your DTI (debt to income) and a house that was affordable without it is now outside of your price range.
Equipment Breakdown. TVs, HVAC systems, and other appliances break down or are damaged. For a low yearly charge, you can be covered. It is a nice feeling to know you will not be responsible for hundreds or even thousands of dollars in repairs.
Identity Theft. Many carriers offer this at a low cost to provide you with identity theft protection. The world gets more complicated every day, and this is a smart, and cheap way, to protect yourself from online dangers.
Water Damage. Storms can cause water damage to your home. Leaking pipes also cause problems. Be sure to check that your Fort Myers homeowners insurance policy has adequate coverage for water damage. The age of your home is also hugely important here. You will likely start facing coverage restrictions if your house is over 30 years old. There are options for a partial or full buyback of this important coverage, but only certain carriers offer that. Please call us to review your options.
The team at Goodlad & Swank Insurance works hard every day to offer the most coverage for your money. We strive to offer only the most competitive and thorough rates of any insurance agency in the great State of Florida. Your home is your castle, and we will work with you to provide ways to make your most important investment safer secure. Contact us today to get started.
We insure primary homes, secondary and seasonal homes, condo units, as well as property you own and rent to others.
We provide coverage for cars, motorcycles, motor homes and recreational vehicles. We provide the best price and coverage.
Our business is protecting your business from the risks you face everyday, whether your business is large or small.
At Goodlad & Swank, we are proud to offer a full suite of insurance options.
Find out your risk and get protected. We offer coverage through the National Flood Insurance Program as well as private insurance carriers.
Whether life insurance is needed for your family or your business we can help you find the right policy at the best possible price.
Your property’s risk of damage from a hurricane in Florida is elevated. If the past has taught us anything, it’s to be prepared.
If you are a renter, you should have renters insurance. You will get the coverage you need at a price that fits your budget.

We not only help clients prepare for the unknown. We also provide various resources to understanding Florida’s Insurance options. Through our partnerships with top rated insurance companies, our affiliations and community resources, we can help you navigate through the insurance world.
Don’t just take our word for it. We’re proud to be able to serve our customers.

This is an amazing company to do business with. I have several properties and slowly I have changed all properties to be with Goodlad & Swank Insurance.
Fast, courteous, professional service with comparable rates. What else do you need?